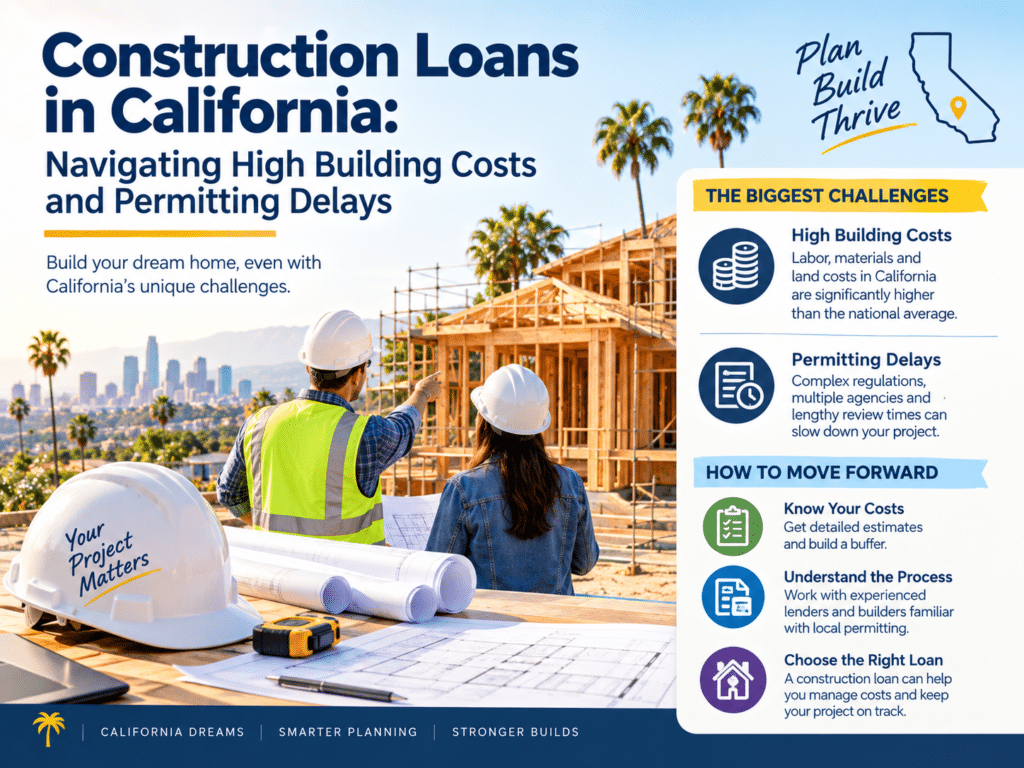
Two things decide whether a California construction project finishes on plan: the budget holding up and the approvals arriving when you assumed they would. A construction loan sits on top of both. It funds in stages tied to work completed, which means a delay in the field or at the counter becomes a financing problem rather than just a scheduling one.
California has statutory deadlines for much of the approval process, and knowing them is genuinely useful. They tell you what a public agency is required to do and by when, which is the difference between a schedule built on hope and one built on the code. This article covers those deadlines with the sections cited, how construction loan draws actually work, and how to build a budget that survives contact with a real project.
How a construction loan differs from a purchase mortgage
A purchase mortgage funds once, at closing. A construction loan funds progressively as the project advances.
- Money is released in draws. Funds are disbursed in stages as work is completed and verified, rather than in a lump sum up-front.
- Inspections gate the money. An inspection or third-party review typically precedes each draw.
- The budget is part of the loan. The lender underwrites the scope of work, the budget, and often the builder, alongside the borrower and the property.
- The loan has a defined end. Construction financing is temporary and is replaced by, or converts to, permanent financing.
- Changes have to be processed. A change to the scope generally means a change order that the lender reviews. Work performed outside the approved budget can create funding gaps.
Two broad structures exist. A construction-to-permanent loan converts to permanent financing when the project is complete. A standalone construction loan is paid off separately, by a refinance or a sale. Which is available depends on the lender, the project, and the borrower.
What California law actually requires of permitting agencies
Permitting timelines vary by jurisdiction, and no article can tell you how long your city takes. What state law does provide is a set of deadlines that apply to public agencies. These come from the Permit Streamlining Act and related sections of the Government Code.
Deciding whether your application is complete
Under Government Code section 65943, a public agency must determine in writing whether a development project application is complete not later than 30 calendar days after receiving it. If the agency finds the application incomplete, it must give the applicant an exhaustive list of the items that were not complete, limited to items actually on the agency’s submittal checklist. If the written determination is not made within that period and the application states that it is an application for a development permit, the application “shall be deemed complete.”
Two more provisions matter in practice. When you resubmit, a new 30-day period begins. And if the agency again determines the application is incomplete, there is an appeal process, with a final written determination required not later than 60 calendar days after the agency receives the written appeal.
This section was amended by Statutes of 2025, Chapter 22 (AB 130), effective June 30, 2025.
Deciding the project itself
Government Code section 65950 sets deadlines for a lead agency to approve or disapprove a development project. The applicable period depends on the environmental review path:
| Environmental review path | Deadline to approve or disapprove |
|---|---|
| Environmental impact report certified | 180 days from certification |
| EIR certified, qualifying housing development project | 90 days from certification |
| EIR certified, qualifying housing project meeting the statute’s affordability and financing conditions | 60 days from certification |
| Negative declaration adopted | 60 days from adoption |
| Project exempt from CEQA | 60 days from the exemption determination |
| Project subject to ministerial review | 60 days from receipt of a complete application |
The statute also allows an applicant and a public agency to agree in writing to extend a time limit.
Permits after entitlement
Getting a project entitled is not the end of the approval path. Building, grading, and other permits that follow are called post-entitlement phase permits, and Government Code section 65913.3 sets deadlines for those as well.
After a local or state agency determines that an application for a post-entitlement phase permit is complete, the agency must complete its review and either return a full set of comments with a comprehensive request for revisions, or return the approved permit application, within:
- 30 business days for housing development projects with fewer than 26 units.
- 60 business days for housing development projects with 26 units or more.
The statute also requires agencies to publish the list of information required from applicants and to post examples of a complete application and a complete set of post-entitlement phase permits.
What these deadlines do and do not give you
They give you a documented basis for a schedule and a reference point when a project stalls. They do not guarantee that a specific permit will issue on a specific date; they do not apply uniformly to every project type, and they contain conditions and exceptions this summary does not reproduce. Your jurisdiction’s own process, staffing, and requirements sit on top of them. Confirm the current process with the city or county building or planning department that has authority over your parcel, and involve a land use attorney where the stakes justify it.
Building a budget that survives the project
Construction costs move, and they move differently by region, project type, and trade. This article does not publish cost figures, because a number without a date, a geography, and a project type is worse than no number at all. What follows is how to structure a budget so that changes do not break the financing.
- Get a line-item budget, not a lump sum. Lenders underwrite the scope. A single number tells nobody anything, including you.
- Build in a contingency line. Ask your lender how contingency is treated in their draw schedule and whether unused contingency can be released.
- Price the current bid, not last year’s. Bids age. If a bid is months old, expect it to be revisited.
- Separate hard costs from soft costs. Permits, fees, design, engineering, surveys, and inspections are real money and are frequently underestimated.
- Account for the carrying period. A longer build means a longer period of carrying the project. Ask how interest is handled during construction and whether an interest reserve is part of the loan.
- Ask what happens if a bid comes in over. Every project has a moment where a number changes. Know in advance whether that means additional borrower funds, a change order, or a rebudget.
- Confirm who pays for what and when. Deposits to suppliers, long-lead items, and mobilization costs often land before the first draw.
Your contractor is part of the underwriting
Lenders generally review the builder alongside the borrower and the project. California also gives you specific consumer protections worth knowing.
Licensing
Contractor licensing in California is administered by the Contractors State License Board. Business and Professions Code section 7048 exempts work where the aggregate contract price for labor, materials, and all other items is less than $1,000, treating it as casual, minor, or inconsequential, and only where the work does not require a building permit. That threshold was raised by Statutes of 2025, Chapter 67 (AB 1170), effective January 1, 2026. The exemption does not apply to a person who advertises as a contractor or who employs another person to perform the work, and it cannot be created by splitting a larger job into smaller contracts.
Practical version: construction work of any real size requires a licensed contractor. Verify the license through the Contractors State License Board’s own license lookup before you sign, and confirm the classification covers the work.
The contract and the deposit
For home improvement contracts, Business and Professions Code section 7159.5 requires the contract to be in writing and to include the agreed contract amount in dollars and cents. On the deposit, the statute is specific: where a down payment will be charged, “the down payment shall not exceed one thousand dollars ($1,000) or 10 percent of the contract amount, whichever amount is less.”
That is a limit on what a contractor may take up front under a home improvement contract. It is a separate matter from any down payment or equity a lender requires, and the two should not be confused. The same section also requires a schedule of payments in dollars and cents, referencing the work, services, materials, and equipment involved, where payments are made before completion.
Common mistakes
- Building the schedule on an assumed permit timeline. Ask the jurisdiction, and know the statutory deadlines that apply to them.
- Submitting an incomplete application. A resubmittal restarts a 30-day completeness clock under Government Code section 65943.
- Treating entitlement as the finish line. Post-entitlement permits have their own process and their own deadlines.
- Starting work outside the approved budget. Unapproved work can create a funding gap that the loan will not cover.
- Skipping the license check. Verify with the Contractors State License Board, not with a business card.
- Paying a large deposit. For home improvement contracts, the statutory cap is the lesser of $1,000 or 10 percent of the contract amount.
- No contingency. A budget with no room absorbs no surprises.
- Not planning the exit. Know before you start whether the loan converts to permanent financing or has to be refinanced or repaid separately.
Frequently asked questions
How long does a California agency have to tell me if my application is complete?
Government Code section 65943 requires a public agency to determine in writing whether a development project application is complete not later than 30 calendar days after receiving it. If that written determination is not made in time and the application states that it is an application for a development permit, the application is deemed complete. A resubmittal starts a new 30-day period.
How long does the agency have to approve or deny the project?
Government Code section 65950 sets the deadline based on the environmental review path: generally 180 days after certification of an environmental impact report, 90 or 60 days for qualifying housing development projects meeting the statute’s conditions, 60 days after adoption of a negative declaration, 60 days after a CEQA exemption determination, and 60 days from receipt of a complete application for ministerial review. Conditions and exceptions apply, and the applicant and agency may agree in writing to an extension.
What about building permits after the project is approved?
Those are post-entitlement phase permits. Under Government Code section 65913.3, after the application is determined complete, the agency generally must complete review and respond within 30 business days for housing development projects with fewer than 26 units, or 60 business days for projects with 26 units or more.
How does a construction loan pay out?
In draws tied to completed work, typically with an inspection or review before each disbursement, rather than as a lump sum at closing. The specific draw schedule and inspection process vary by lender and program.
What is the difference between construction-to-permanent and standalone construction financing?
A construction-to-permanent loan converts to permanent financing at completion. A standalone construction loan is repaid separately, generally by a refinance or a sale. Availability depends on the lender, the project, and the borrower, and all financing is subject to underwriting approval.
How much should I budget for construction costs in California?
Costs vary substantially by region, project type, scope, and materials, and they change over time. This article deliberately does not publish cost figures. Get current line-item bids from licensed contractors for your specific project, and treat any general figure you find online as a starting point for questions rather than a number to plan on.
Do I need a licensed contractor?
Business and Professions Code section 7048 exempts work where the aggregate contract price is less than $1,000 and the work does not require a building permit, treating it as casual or minor. That threshold rose to $1,000 effective January 1, 2026. The exemption has significant limits and does not apply to someone advertising as a contractor or employing others, and a larger job cannot be split into smaller contracts to fit under it. Verify any contractor’s license and classification with the Contractors State License Board before signing.
How much of a deposit can a contractor ask for?
For home improvement contracts, Business and Professions Code section 7159.5 provides that where a down payment is charged, it “shall not exceed one thousand dollars ($1,000) or 10 percent of the contract amount, whichever amount is less.” That is separate from anything your lender requires.
Build the schedule on the statutory deadlines and on what your jurisdiction actually tells you, not on assumptions. Know that a completeness determination is due within 30 calendar days, that project decision deadlines run from the environmental review path, and that post-entitlement permits carry 30 or 60 business day review periods depending on unit count. Get a line-item budget with a contingency, verify your contractor’s license, keep the deposit within the statutory cap, and settle how the construction loan gets taken out before you break ground.
Sprint Funding can walk through how a construction loan would be structured for a specific project. Start at the construction loan page, consider a bridge loan if timing is the constraint, find a mortgage advisor, or contact the office for a written quote.
About this article
Sprint Funding, Inc. publishes this article and offers the loan products described in it. Treat it as educational content from a company with a commercial interest, not as independent advice. Nothing here is a loan offer, a commitment to lend, or legal, tax, or construction advice. Loan options vary by borrower qualifications, and all financing is subject to underwriting approval. No rates, payments, or loan terms are quoted here. Ask a licensed loan professional for a written quote, and review your Loan Estimate or term sheet and your note before you commit.
Statutory summaries are drawn from California Government Code sections 65943, 65950, and 65913.3 and California Business and Professions Code sections 7048 and 7159.5, reviewed on August 4, 2026. Statutes are summarized, not reproduced in full, and each contains conditions and exceptions not covered here. Statutes change, and amendment dates are noted where they are recent. Nothing here is a determination about any specific project, application, permit, or contract. Confirm requirements with the city or county with authority over your parcel and with the Contractors State License Board, and consult a qualified attorney for advice on your situation.
Sprint Funding, Inc., NMLS ID 348300. State licensing is listed at sprintfunding.com/state-licenses. Sprint Funding is a private company and is not a government agency, and is not affiliated with or endorsed by the Contractors State License Board, the California Department of Housing and Community Development, or any city or county.