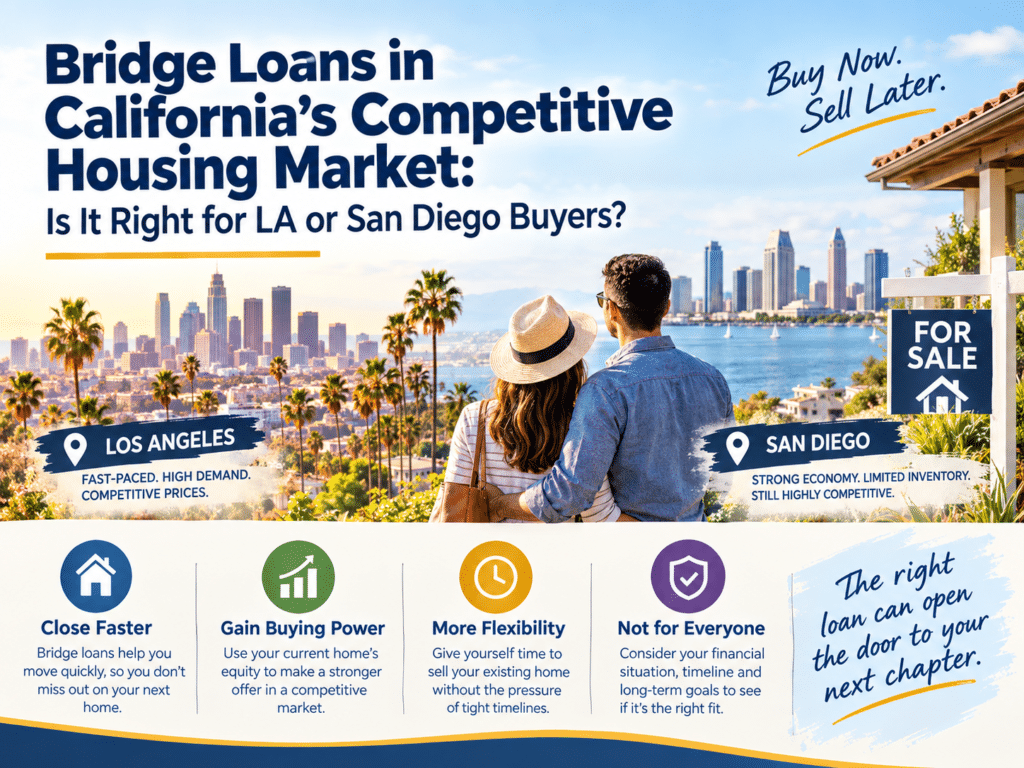
Most buyers who look at a bridge loan are solving one specific problem: they need the equity in the home they own to buy the home they want, and the two transactions will not line up on their own.
In competitive Southern California markets, that problem has a second edge. An offer that depends on selling another property first competes against offers that do not. A bridge loan is one way to remove that dependency. It is also short-term, more expensive financing that puts a second obligation on the household while it is outstanding. This article works through when that trade is worth making, and when it is not.
The problem a bridge loan is built to solve
Say you own a home with meaningful equity and you want to buy your next one. You have three basic sequences:
- Sell first, then buy. Clean financially. It can leave you without a home between transactions, and it means shopping under time pressure.
- Buy first with a sale contingency. Keeps you in your home. It also makes your offer weaker, because the seller is accepting a deal that can fall apart on a transaction they cannot control.
- Buy first using bridge financing. Removes the contingency and the timing gap. It costs more and it means carrying two obligations for a period.
The bridge loan exists to make option three possible. Whether that is the right call depends on your equity, your carrying capacity, and how firm your exit is.
Why the contingency question is sharper in LA and San Diego
Southern California purchases at the upper end of the market often sit above conforming loan limits, which puts them in jumbo territory where underwriting is set lender by lender. The county limits themselves differ, which changes where that line falls.
| County | 2026 one-unit conforming limit |
|---|---|
| Los Angeles | $1,249,125 |
| Orange | $1,249,125 |
| San Diego | $1,104,000 |
| Riverside | $832,750 |
| San Bernardino | $832,750 |
The practical read: a Los Angeles County buyer has roughly $145,000 more conforming loan room than a San Diego County buyer on a one-unit property, and both have far more than a buyer in Riverside or San Bernardino County. Where your purchase lands relative to that line affects which financing paths are open, and it affects how a bridge loan fits into the plan for taking out permanent financing later.
Market conditions in Los Angeles and San Diego are not identical, and they change. Rather than working from a general characterization of either market, ask your agent for current, dated data on the specific submarket and price band you are shopping in. How often sellers accept contingent offers in your price range is a local question, and the answer changes through the year.
A decision framework
Four questions decide most of these cases.
1. How firm is the exit?
A bridge loan is repaid from a specific future event, almost always the sale of your current home. The strength of that exit is the single biggest factor. A property that is already under contract is a different risk than one that has not been listed. Be honest with yourself here, because the lender will be.
2. Can you carry both obligations?
For some period, you may be responsible for the existing mortgage, the bridge loan, and the new home’s costs. Some structures reduce or defer payments during the bridge period, and availability varies by lender and program. Run the scenario where your sale takes longer than you expect, and see whether it still works.
3. How much equity is actually available?
Lenders limit how much they will lend against property value. That limit varies by lender, property type, and structure, so ask what applies to your file rather than assuming. Selling costs, the existing loan payoff, and any liens come out before you see proceeds.
4. What does the contingency actually cost you?
This is the question buyers skip. Before paying for bridge financing, find out what a contingent offer really costs in your situation. In some cases, a seller will accept a contingent offer with a shorter timeline or a larger deposit. In others, the offer will not be considered. Your agent can tell you which situation you are in, and that answer determines whether bridge financing is buying you something valuable or something you did not need.
Alternatives worth pricing first
| Alternative | How it addresses the problem | What to watch |
|---|---|---|
| Sell first, rent short term | Removes financing complexity entirely | Two moves, and you shop on a clock |
| Contingent offer | No extra financing cost | Weaker offer. May not be viable in your price band |
| Rent-back from your buyer | Sell first while staying in the home briefly | Requires a cooperative buyer. Terms are negotiated |
| Home equity financing on the departing home | Accesses equity without a full bridge structure | Availability can be restricted once a home is listed. Ask early |
| Delayed financing after a cash purchase | Buy without financing, then finance after closing | Requires cash. Program rules apply |
| Bridge loan | Removes the contingency and the timing gap | Short-term cost, dual obligations, exit risk |
Price at least two of these against each other before committing. A bridge loan can be the right answer, and it should win on comparison rather than by default.
Who tends to be a good fit?
- Owners with substantial equity in a property that is listed or under contract.
- Buyers competing in a price band where contingent offers are not being accepted.
- Households with the capacity to carry both obligations if the sale runs long.
- Buyers who need to close on a specific timeline that a sale cannot match.
- Owners whose next purchase needs work before it can qualify for permanent financing.
Who should think twice?
- Anyone whose exit depends on a sale price they have not tested with the market.
- Households that would be strained by carrying two obligations for longer than planned.
- Buyers who have not yet confirmed that a contingent offer would actually be rejected.
- Anyone who has not read the extension terms in the loan documents.
- Buyers who have not lined up the permanent financing that will take out the bridge loan.
Risks to plan for
- The sale takes longer than expected. Ask what extension options exist, what they cost, and whether they are at the lender’s discretion, before you close.
- The sale price comes in lower. If proceeds fall short of the payoff, the difference has to come from somewhere. Work that scenario in advance.
- Two obligations at once. This is the part that strains households, and it is predictable, which means it is plannable.
- The loan is secured by real estate. Default has consequences for the property. Read the note.
- The permanent financing changes. Your take-out loan is underwritten on its own terms when you get there. Do not assume today’s approval carries forward unexamined.
Frequently asked questions
What is a bridge loan in simple terms?
Short-term financing secured by real estate, used to cover the gap between buying one property and selling or refinancing another. It is repaid from a specific event, usually the sale of the departing home.
Is a bridge loan a good idea in the Los Angeles or San Diego market?
It depends on your equity, your ability to carry two obligations, and how firm your exit is. It also depends on whether a contingent offer would actually be rejected in your price band, which is a local question worth answering before you pay for financing to avoid it.
How is the amount determined?
Lenders limit how much they will lend against property value, and the applicable limit varies by lender, property type, and structure. Existing loans, liens, and selling costs reduce what is available. Ask for the figure that applies to your file.
Does the conforming loan limit apply to a bridge loan?
Conforming loan limits govern loans eligible for purchase by Fannie Mae and Freddie Mac. Bridge loans are generally not agency products, so lender guidelines govern instead. The county limits still matter for the permanent financing that will replace the bridge loan, and those limits differ by county: $1,249,125 in Los Angeles County and $1,104,000 in San Diego County for a one-unit property in 2026.
What if my house does not sell in time?
That depends on your loan documents. Some notes include extension options, generally for a fee and subject to lender approval. Others do not. Ask before closing, and tell your lender early if the timeline is slipping.
Can I use a bridge loan if my home is not listed yet?
Some lenders will consider it and some will not, and an unlisted property generally presents a weaker exit. Expect more scrutiny of value and of your plan.
Is a bridge loan the same as a HELOC?
No. A home equity line of credit is revolving credit secured by a property you keep. A bridge loan is short-term financing tied to a specific transition and a specific payoff event. Availability of home equity financing can also be restricted once a home is listed for sale.
How do I compare offers from bridge lenders?
Compare the full structure rather than one figure: all fees in writing, prepayment terms, extension rights and their cost, how and when funds are disbursed, what happens if the sale is delayed, and whether the lender is licensed in the state where the property sits. You can verify a company and a loan originator on NMLS Consumer Access.
A bridge loan buys you the ability to make a non-contingent offer and to move once instead of twice. It costs more than permanent financing and it puts two obligations on the household until the sale closes. Answer four questions first: how firm the exit is, whether you can carry both obligations if the sale runs long, how much equity is genuinely available, and whether a contingent offer would actually be rejected in your price band. If the answers line up, it is a reasonable tool. If they do not, one of the alternatives is likely to serve you better.
Sprint Funding works with buyers across San Diego and Los Angeles. Start at the bridge loan page, compare against conventional financing, find a mortgage advisor, or contact the office for a written quote and a side-by-side comparison.
About this article
Sprint Funding, Inc. publishes this article and offers the loan products described in it. Treat it as educational content from a company with a commercial interest, not as independent advice. Nothing here is a loan offer, a commitment to lend, or legal, tax, or financial advice. Loan options vary by borrower qualifications, and all financing is subject to underwriting approval. No rates, payments, or loan terms are quoted here. Ask a licensed loan professional for a written quote, and review your Loan Estimate or term sheet and your note before you commit.
Conforming loan limit figures come from the Federal Housing Finance Agency’s 2026 county-level conforming loan limit values and apply to the counties named. Figures were verified on August 4, 2026, and limits reset annually. This article does not state current market conditions in any city or price band, because those change; ask a local real estate professional for current, dated data on your submarket.
Sprint Funding, Inc., NMLS ID 348300. State licensing is listed at sprintfunding.com/state-licenses. Sprint Funding is a private company and is not a government agency.