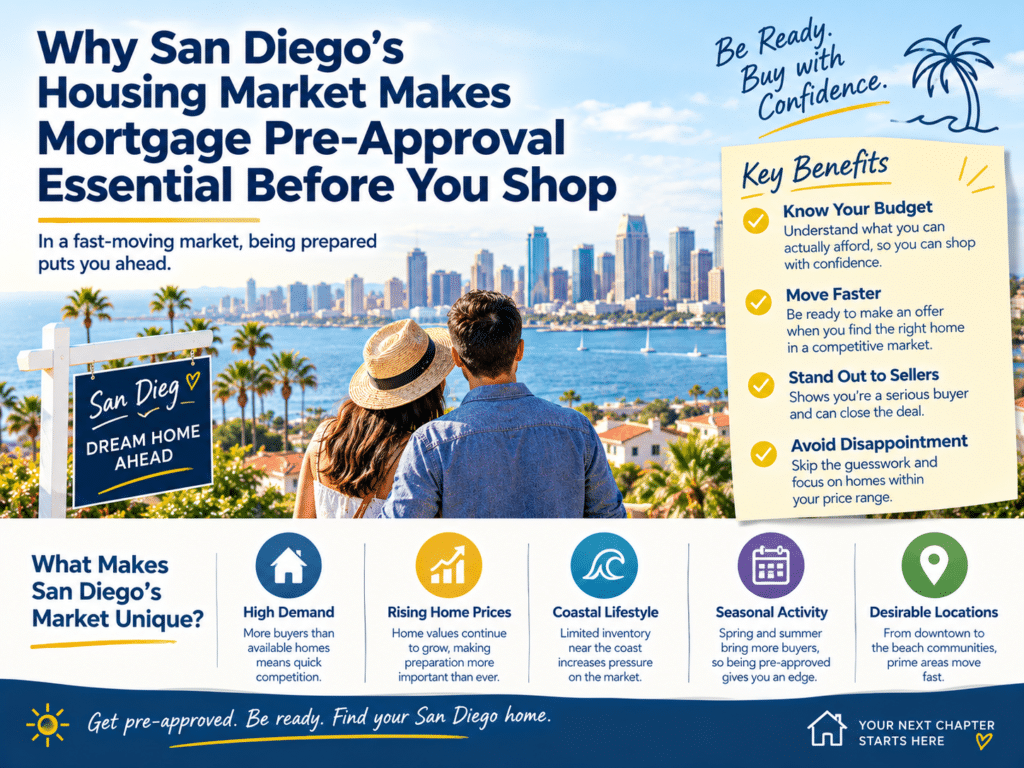
Shopping for a home without a pre-approval is shopping without knowing your budget. In a market where prices commonly push against and past the conforming loan limit, that is an expensive way to learn what you can borrow.
There is a second reason, and it has nothing to do with you. A seller comparing offers is comparing risk. An offer backed by a lender that has reviewed documentation is a different proposition from an offer backed by nothing but optimism. Sellers and their agents read that difference.
This article covers what a pre-approval actually is, how it differs from the three terms it gets confused with, what to gather before you start, and the San Diego specifics worth knowing.
Four terms that are not interchangeable
These words get used loosely, including by people in the industry. They mean different things, and the difference matters at exactly the moment it is most expensive to get wrong.
| Term | What it generally means | How much weight it carries |
|---|---|---|
| Pre-qualification | An early estimate. CFPB notes that some lenders issue a prequalification letter based on unverified information that you report | Useful for orientation. Weakest with sellers |
| Pre-approval | CFPB describes it as “a letter from a lender that says the lender is generally willing to lend to you, up to a certain amount and based on certain assumptions,” and notes that some lenders issue one only after reviewing verified information | Meaningful to sellers. Still not a commitment |
| Conditional approval | Underwriting has reviewed the file and issued an approval that lists items still required | Substantial. The remaining list is specific |
| Clear to close | Conditions are satisfied and closing documents can be drawn | The strongest position before funding |
The sentence to remember comes straight from CFPB: a pre-approval “is not a guaranteed loan offer, but it should provide enough information for sellers in your area to take it seriously.”
Both halves of that matter. It is not a guarantee. It is also genuinely useful.
What a pre-approval does for you
- It sets a real budget. A number that came out of a document review is worth more than a number from an online calculator.
- It surfaces problems early. A credit issue, a documentation gap, or an income structure that needs explaining is far cheaper to fix in week one than during escrow.
- It strengthens your offer. Sellers weigh the likelihood that a deal closes. A reviewed file reads as lower risk.
- It speeds you up later. Much of the work needed for final approval is already done.
- It tells you which programs fit. Conventional, FHA, VA, and other options have different requirements, and the comparison is concrete once someone has looked at your file.
What a pre-approval does not do
- It does not guarantee funding. Final approval depends on underwriting, the property, the appraisal, and title.
- It does not lock anything in. Pricing is a separate conversation with its own timing and its own agreement.
- It does not survive a changed file. Changing jobs, opening new credit, or making a large deposit or purchase can change the analysis.
- It does not last forever. Letters carry expiration dates, and the documentation behind them ages.
- It does not evaluate the property. That comes later, and it can change the outcome.
What to gather before you start
Requirements vary by lender and by program, and self-employed borrowers, retirees, and borrowers with rental income should expect a somewhat different list.
| Category | Typically requested |
|---|---|
| Identity | Government-issued photo ID for each borrower. |
| Income | Recent pay statements, W-2s or 1099s, and often tax returns. Self-employed borrowers should expect business returns and financial statements. |
| Assets | Recent bank and retirement or brokerage statements, all pages, including funds for closing and reserves. |
| Debts | Statements for loans, lines of credit, student loans, and any support obligations. |
| Housing history | Current landlord or mortgage information, and property tax and insurance details for property you own. |
| Program specific | Certificate of Eligibility for a VA-backed loan. Other programs have their own documents. |
| Explanations | Written explanations for large deposits, employment gaps, or credit events. |
Send complete documents, including every page of multi-page statements. Partial uploads are the most common cause of avoidable delay.
San Diego specifics worth knowing
The loan amount decides which rulebook applies
San Diego County’s 2026 conforming loan limit is $1,104,000 for a one-unit property, per the Federal Housing Finance Agency. A loan at or below that figure can be a conforming loan. Above it, the loan is generally a jumbo, and jumbo guidelines are set by individual lenders and investors rather than by Fannie Mae and Freddie Mac.
That line affects what documentation you should expect and how much reserve the program may require. If your target amount is near it, ask to be pre-approved for both structures so you know where you stand either way.
The county limit follows the property, not you
The applicable figure is the one for the county where the property sits. A buyer living in Riverside County and shopping in San Diego County uses San Diego County’s figure, which is $271,250 higher than the national baseline of $832,750 that applies in Riverside County.
Program limits do not all work the same way
- Conventional: the conforming limit above applies.
- FHA: HUD publishes its own county limits, separately from FHFA. Look up San Diego County’s current figure at HUD’s FHA Mortgage Limits tool rather than assuming it matches the conforming number.
- VA: VA states that borrowers with full entitlement do not have a loan limit, subject to affordability and the appraisal supporting the price. Lender approval is still required.
Getting this straight during pre-approval, rather than after you write an offer, is the whole point of doing it early.
How to make the pre-approval hold up
- Keep your financial picture still. Between pre-approval and closing, avoid new credit, large unexplained deposits, big purchases, and job changes where you can. If something is unavoidable, tell your loan officer before it happens.
- Keep documents current. Statements and pay records age. Expect to refresh them.
- Ask what the letter is based on. Verified documentation or stated information? The answer determines what the letter is worth.
- Ask what it does not cover. Every letter carries assumptions. Know them.
- Get it in writing, and read it. Including the expiration date.
Common mistakes
- Treating a pre-qualification as a pre-approval. Different basis, different weight.
- Assuming a pre-approval guarantees the loan. CFPB says plainly that it does not.
- Shopping above the letter amount. If you want a higher number, get the file reviewed for it rather than hoping.
- Opening new credit mid-process. A new account can change the analysis.
- Ignoring the property side. Appraisal, condition, HOA, and title can all affect the outcome after your file is approved.
- Letting the letter expire. Ask what refresh takes before you are in a hurry.
- Not asking about program fit. The right program for your file may not be the one you assumed.
- Waiting until you find a house. The document gathering takes as long as it takes, and it does not compress just because you found the right place.
Frequently asked questions
What is the difference between pre-qualification and pre-approval?
Per the Consumer Financial Protection Bureau, some lenders issue a prequalification letter based on unverified information that you report, and issue a preapproval letter only after reviewing verified information. Ask any lender which basis their letter uses, because the terms are used differently across the industry.
Does a pre-approval guarantee I will get the loan?
No. CFPB states plainly that a pre-approval “is not a guaranteed loan offer,” while noting that it should give sellers in your area enough information to take it seriously. Final approval depends on underwriting, the property, the appraisal, and title, and all financing is subject to underwriting approval.
How long does a pre-approval last?
Letters carry expiration dates, and the supporting documentation ages as well. The specific period varies by lender, so ask what yours is and what refreshing it requires.
Does getting pre-approved affect my credit?
A pre-approval generally involves a credit check, which you authorize. Ask your loan officer what will be pulled and when. If you are comparing lenders, ask each one how their process handles credit inquiries.
How much should I get pre-approved for in San Diego?
That depends on your income, debts, assets, credit, and the program. One local factor worth knowing is that San Diego County’s 2026 conforming loan limit is $1,104,000 for a one-unit property, so amounts above that generally move into jumbo guidelines set by individual lenders and investors.
Can I get pre-approved if I am self-employed?
Yes, and you should expect a more detailed document request, often including business tax returns and financial statements. Starting early matters more for self-employed borrowers than for anyone else.
Should I get pre-approved by more than one lender?
Comparing lenders is reasonable and is generally encouraged in consumer guidance. Ask each for the basis of their letter and a written breakdown of costs, and ask how they handle credit inquiries during shopping.
What happens between pre-approval and closing?
Your file goes through full underwriting, the property is appraised, title work is completed, and the lender issues conditions to clear. Once those are satisfied, the file becomes clear to close.
Get pre-approved before you shop, not after you fall in love with a listing. Know which of the four stages your letter represents, because they carry different weight. Gather complete documents early, especially if your income is self-employed or otherwise complicated. And find out where your target loan amount sits relative to San Diego County’s $1,104,000 conforming limit, since that line changes which guidelines apply.
A pre-approval is not a guarantee. It is the difference between shopping with information and shopping with a hope.
Sprint Funding can review your file and explain exactly what its letter is based on. Start by finding a mortgage advisor, compare conventional, FHA, and VA options, or contact the office.
About this article
Sprint Funding, Inc. publishes this article and offers the loan products described in it. Treat it as educational content from a company with a commercial interest, not as independent advice. Nothing here is a loan offer, a commitment to lend, or legal, tax, or financial advice. Loan options vary by borrower qualifications, and all financing is subject to underwriting approval. No rates, payments, or loan terms are quoted here. Ask a licensed loan professional for a written quote, and review your Loan Estimate and note before you commit.
Definitions of prequalification and preapproval are drawn from Consumer Financial Protection Bureau consumer guidance, reviewed on August 4, 2026. The San Diego County and national conforming loan limit figures come from the Federal Housing Finance Agency’s 2026 county-level conforming loan limit values and reset annually. FHA county limits are published separately by HUD. This article does not describe current market conditions in San Diego, because those change; ask a local real estate professional for current, dated data on your submarket.
Sprint Funding, Inc., NMLS ID 348300. State licensing is listed at sprintfunding.com/state-licenses. Sprint Funding is a private company and is not a government agency, and is not endorsed by CFPB, FHFA, HUD, or VA.